MARIJUANA
Two Republicans Ask Treasury to Keep the Marijuana Tax Penalty
Two GOP lawmakers want Treasury to keep 280E in force for marijuana businesses after medical cannabis moved to Schedule III.

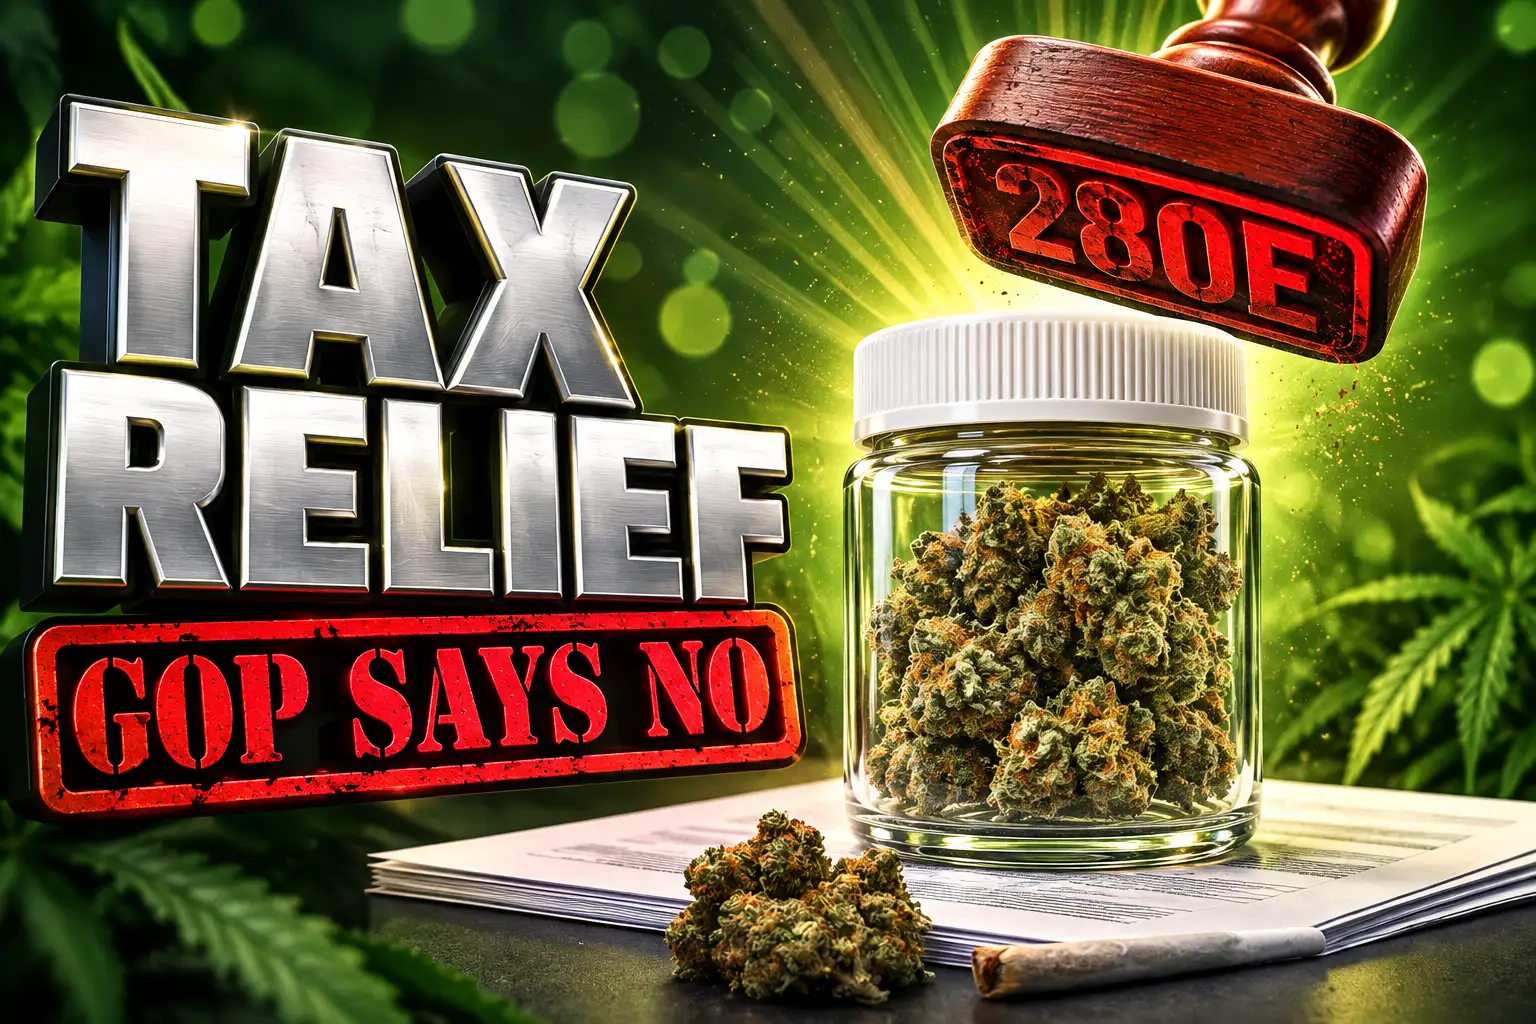
Two Republican lawmakers asked Treasury Secretary Scott Bessent on June 3, 2026, to withhold ordinary tax deductions from marijuana businesses after medical cannabis moved to Schedule III. Sen. James Lankford of Oklahoma and Rep. Jodey Arrington of Texas want that penalty kept in force, including for years already closed.
The request lands on a split their own party created. Acting Attorney General Todd Blanche’s April 23, 2026, order put FDA-approved marijuana products and state-licensed medical marijuana in Schedule III. Adult-use cannabis stayed in Schedule I, where the old tax trap still bites.
Two Republicans Asked Treasury to Keep 280E
Lankford and Arrington sent their letter to Treasury Secretary Bessent after reading the Justice Department’s April rule as a tax event, not only a scheduling event. They wrote that they have “long been concerned about the potential fiscal and societal consequences of rescheduling,” which is why they had already introduced a bill to deny marijuana businesses federal deductions and credits no matter the drug’s schedule.
In addition, we were particularly troubled that the final rule encouraged the Secretary of the Treasury to consider providing retrospective tax relief to marijuana businesses.
James Lankford and Jodey Arrington, letter to Treasury Secretary Scott Bessent, June 3, 2026
The letter argues that a state medical license is a weak screen for federal tax benefits. It says many licensed operators sell in both medical and adult-use markets, so Treasury would have to split activity that qualifies from activity that does not. It also treats state boards as uneven, pointing to Oklahoma, California, and Maine as places where a license has not, in their view, equaled clean compliance.
They asked Bessent to answer six questions by June 29, 2026, the same day DEA’s broader rescheduling hearing was set to open.
THE SIX QUESTIONS FOR TREASURY
- Prior years: What “retrospective tax relief” means, and how many past tax years Treasury might open.
- Compliance screen: How Treasury would confirm a candidate shop had not diverted product, laundered money, or taken part in trafficking.
- Revenue loss: The estimated drop in federal receipts if marijuana businesses get ordinary deductions and credits.
- Households: How prior-year relief for those businesses would help American families.
- Deficits: The effect on annual deficits and the national debt of a retroactive tax benefit.
- Authority: What statute allows a tax benefit for owners who sold or made a product against federal law.
Those questions are the tell. The pair is not only arguing about 2026 returns. They are trying to stop refunds for years when the same medical operators were still in Schedule I.
The April Order That Created the Tax Opening
Blanche signed the April order on medical marijuana under treaty-based scheduling authority in the Controlled Substances Act, a path that let the department act without finishing the older notice-and-comment file. The Justice Department said the move followed President Trump’s December 18, 2025, executive order, “Increasing Medical Marijuana and Cannabidiol Research.”
The Department of Justice is delivering on President Trump’s promise to expand Americans’ access to medical treatment options. This rescheduling action allows for research on the safety and efficacy of this substance, ultimately providing patients with better care and doctors with more reliable information.
Todd Blanche, Acting Attorney General, Justice Department press release, April 23, 2026
The order covers two buckets. One is FDA-approved drug products that contain marijuana. The other is marijuana subject to a state license to make, distribute, or dispense it for medical use. Adult-use product is outside both buckets. DEA was told to build a faster registration path for qualifying state medical licensees, and a separate hearing was set to weigh whether all marijuana, not only medical, should move to Schedule III.
A Congressional Research Service legal sidebar dated April 30, 2026, spelled out the tax hinge. To the extent marijuana sits in Schedule I or II, Section 280E of the tax code blocks certain federal deductions. Move the medical activity to Schedule III, and that section’s own trigger no longer fits. Industry tax analyses have long put effective rates under 280E at 70% or higher, which is the cash squeeze the April order was written to ease for medical licensees going forward.
THE FEDERAL CANNABIS TAX CALENDAR
- December 18, 2025: Trump directs the attorney general to move on medical marijuana and CBD research, including the stalled rescheduling file.
- April 23, 2026: Blanche’s order places FDA-approved marijuana products and state-licensed medical marijuana in Schedule III and tees up a new hearing on a wider move.
- June 3, 2026: Lankford and Arrington ask Bessent to keep 280E in force and to explain any plan for prior-year relief.
- June 29, 2026: Their answer deadline and the start date for DEA’s hearing on rescheduling marijuana beyond the medical bucket.
- July 15, 2026: The hearing was scheduled to finish; adult-use marijuana has not been moved by a final rule.
The same administration that opened medical 280E relief is the one Lankford and Arrington are asking to close it. That is the fight, not a dispute about whether Blanche signed the order.
Who Still Pays Section 280E After Rescheduling
280E does not name “cannabis shops.” It names trafficking in a Schedule I or II controlled substance and then denies ordinary deductions and credits. Payroll, rent, utilities, and marketing are the costs operators could not subtract the way a liquor store does. Cost of goods sold was the main remaining break, which is why a busy medical counter could still post a huge tax bill on thin profit.
After April 23, 2026, the plant’s federal box depends on how it is licensed and sold. Medical product under a qualifying state license is Schedule III. Adult-use product is still Schedule I. A dual-license operator is running one building under two federal labels.
THE 280E SPLIT AFTER APRIL 23
| Operator type | Federal schedule after April 23, 2026 | Ordinary 280E deductions |
|---|---|---|
| State-licensed medical | Schedule III | The statute’s I/II trigger no longer fits |
| Adult-use, or recreational | Schedule I | Still blocked |
| Dual medical and adult-use license | Medical in III, adult-use in I | Allocation left to Treasury, the letter says |
Lankford and Arrington treat that third row as the reason not to grant relief at all. If Treasury cannot draw a clean line through a dual-license ledger, they want the deduction kept off the table for the medical side too. Accounting shops, meanwhile, have been telling operators not to treat the April order as a green light to amend old returns and pull cash back for Schedule I years.
9,178 Oklahoma Grows and the License Argument
Lankford’s home-state market is the case study in the letter. At the height of Oklahoma’s medical program, they wrote, the state had 9,178 licensed marijuana growing operations. They cited a Texoma High Intensity Drug Trafficking Area report and said law enforcement later shut many of those grows for violations, even though each had, at one point, a state license.
The letter goes further. It claims some licensed operations funneled marijuana to the illicit market and took part in other crimes, including money laundering and human trafficking, and that many were owned and run by Chinese nationals who used state marijuana law as cover. Those are the lawmakers’ charges, tied to the HIDTA paper they footnoted, not a court finding restated here.
From that pile they draw a national rule: a state card should not, by itself, unlock federal tax benefits. California and Maine are named as showing “systemic issues” with state licensing, again in their voice. The policy move they want is simple. If a license is not proof of lawful conduct, Treasury should not pay ordinary deductions, and it should not reopen old years.
That argument collides with the April order’s premise. Blanche’s department treated state medical systems, taken as a whole, as a workable way to meet federal control goals. Lankford is telling Bessent those systems are too leaky to underwrite a tax cut.
How the No Deductions Bill Would Rewrite 280E
The letter points back to a bill the two men had already filed, the No Deductions for Marijuana Businesses Act. Arrington is the sponsor of H.R. 1447 in the 119th Congress. The House referred it to Ways and Means on February 21, 2025. A Senate companion, S. 471, shows actions on February 6, 2025. Neither file is described in Congress’s listings as having reached a floor vote.
The point of the bill, as they restated it to Bessent, is to bar marijuana businesses from federal deductions or credits regardless of the drug’s classification. That is a statute-over-schedule fix. If 280E stops biting when a product leaves Schedule I or II, a new section could put the bite back on by name. It would also outlive a later adult-use rescheduling, which is why they can live with Blanche’s medical order and still try to keep the tax penalty.
That is the same objection that circulated on the right before the April order. In August 2025, commentator Jack Posobiec called rescheduling “a massive corporate handout to Big Leaf,” saying billions would flow in tax deductions. Lankford and Arrington put that complaint into committee drafts, then into a Treasury letter after the White House had already moved medical product.
A letter is not a statute. Without a passed bill, Bessent’s reading of 280E and any prior-year guidance remain the live instruments. That is why two members who already have a bill still need the Treasury secretary to say no.
Adult-Use Cannabis Remains on Schedule I
The April order did not legalize recreational marijuana under federal law. CRS notes that 24 states and the District of Columbia have removed some state criminal bans on adult recreational use, while nearly all states now allow medical programs. Federal law still sits on top of those state files. Unauthorized activity remains a federal crime, including in legalization states.
Congress has, for years, treated medical programs as a special enforcement case. In each budget cycle since FY2015, lawmakers have attached an appropriations rider that bars the Justice Department from spending funds to stop states from carrying out their own medical marijuana laws. Courts have read that rider to reach medical activity, not adult-use activity. Blanche’s medical-only Schedule III order follows that groove. Adult-use product does not.
DEA’s hearing on broader marijuana rescheduling was set to begin June 29, 2026, and to wrap no later than July 15, 2026. The department withdrew an older hearing notice so it could run a tighter calendar on the leftover question: whether marijuana as a whole, including adult-use, should join medical product in Schedule III. That record has not produced a final adult-use rule. Until it does, 280E still applies to recreational sales the old way.
Shops that hold both kinds of licenses are the ones stuck doing two sets of books. The medical grams may fall outside 280E. The adult-use grams may not. Lankford and Arrington say that blur is a reason to deny the medical break. Operators say it is a reason Treasury has to issue allocation rules instead of freezing the whole file.
Prior-Year 280E Refunds and Treasury’s Open Questions
The April order did more than change the schedule. It encouraged the Treasury secretary to consider retrospective relief from 280E for tax years when a state licensee ran under a medical license. That sentence is what Lankford and Arrington called out as especially troubling. It is also the sentence tax advisers have been circling since spring, because a going-forward deduction and a refund check are different pieces of cash.
Going forward, medical operators can plan 2026 as a year when 280E’s I/II hook does not fit their licensed medical sales. Looking back, amended returns for closed years are another fight. Justice Department litigation over refund paths, and adviser notes that the IRS has not treated those amended filings as entitled under current rules, have pushed firms to wait rather than file and hope.
WHAT WE KNOW
- Medical schedule: FDA-approved marijuana products and state-licensed medical marijuana are in Schedule III as of the April 23, 2026, order.
- Adult-use schedule: Recreational marijuana remains Schedule I pending a separate rule.
- Statute text: 280E’s deduction ban is written for trafficking in Schedule I or II substances.
- The ask: Lankford and Arrington want Bessent to refuse ordinary deductions and to define, then tightly limit, any prior-year relief.
WHAT IS UNCONFIRMED
- Bessent’s answers: No public Treasury reply matching the six June 29 questions has been issued as a paired release.
- Refund years: How many prior tax years, if any, Treasury might reopen for medical licensees.
- Dual-license math: How a shop would allocate shared rent, payroll, and other costs between Schedule III medical sales and Schedule I adult-use sales.
- Adult-use final rule: Whether the June-July hearing file ends in a Schedule III transfer for the rest of the plant.
The conservative objection was never really about Blanche’s research language. It was about ordinary deductions landing on a business that federal law still calls trafficking on the adult-use side, and recently called trafficking on the medical side too. The April order tried to split those businesses. The June letter tries to glue the tax treatment back together.
Medical marijuana is in Schedule III. Adult-use marijuana is not. The deductions that follow that medical move are what Lankford and Arrington have asked Bessent to deny, including for years when the same licensees were still in Schedule I.
Disclaimer: This article is news reporting and analysis of federal scheduling and tax developments. It is for information only and is not tax, legal, accounting, or investment advice. It does not tell any operator, investor, or patient whether to file, amend, deduct, or claim a refund, and it does not replace advice from a qualified tax attorney, CPA, or enrolled agent who can review a specific return. Figures, bill statuses, and agency actions reflect the public documents cited here and can change if Treasury, IRS, DEA, or Congress issues new guidance or a new statute.

The Justice Department Told Marijuana Testers They Lack Standing

The DEA Hearing Left Adult-Use Cannabis on Schedule I

Two Republicans Ask Treasury to Keep the Marijuana Tax Penalty

The Cannabis Banking Bill Sits Idle in Tim Scott’s Committee

Indiana’s Two-Ounce Marijuana Bill Died Without a Hearing

Vermont Stripped Psilocybin Legalization and Still Has No Therapy Program

Demecan’s €100 Million Round Was a Sales Bet

Cann Group’s $15 Million Obsidian Facility Ended in a Buyout

Identifying Cannabis Grow Houses: Key Signs to Watch For

White House Drug Office Puts Lev Back on Medical Policy
-
 LAW3 years ago
Vermont Stripped Psilocybin Legalization and Still Has No Therapy Program
-
 CANNABIS3 years ago
Cann Group’s $15 Million Obsidian Facility Ended in a Buyout
-
 CANNABIS2 years ago
Demecan’s €100 Million Round Was a Sales Bet
-
 NEWS2 years ago
Identifying Cannabis Grow Houses: Key Signs to Watch For
-

 CANNABIS2 years ago
DC Padlocked Green Cloud, Then Licensed the Same Owner
-
 LAW2 years ago
New Brunswick’s Cannabis Crackdown Stops at the Reserve Line
-
 MARIJUANA1 year ago
White House Drug Office Puts Lev Back on Medical Policy
-
 CANNABIS2 years ago
Ascend Wellness Kept Its 2024 Bosses and Lost Sales